Health Insurance Premiums Paid for S-Corporation Shareholders
Health Insurance Premiums Paid for S-Corporation Shareholders
Updated for 2026
If your S corporation pays health insurance premiums for you as an owner, those premiums must be added to your W-2 before year-end. Getting this right is what lets you deduct the premiums on your personal return.
Who This Applies To
The rule applies to any shareholder who owns more than 2% of the S corporation and works for it. The IRS calls this person a “2% shareholder-employee.” Premiums for the shareholder’s spouse and dependents are included too.
How It Works
The corporation can pay the premiums directly or reimburse you for them. The policy can be in the corporation’s name or your own. Either way, the corporation deducts the premiums, and the amount must be reported on your W-2.
Premiums you pay personally and never run through the corporation do not qualify.
How It Is Taxed
The premiums go in Box 1 of your W-2. They are subject to federal and California income tax, but not to Social Security, Medicare, federal unemployment, or California UI, ETT or SDI, as long as the premiums are paid under a plan that covers all employees or a class of employees.
On your personal return, you then deduct the same amount as self-employed health insurance. This deduction is not available if you or your spouse were eligible for a subsidized health plan through another employer. The result is that the premiums are deductible, but you do not pay payroll taxes on them.
Why Timing Matters
The amount has to be added through payroll before your final payroll of the year. If it is missed, you can lose the deduction.
What to Do Now
- If we prepare your payroll: send us the total premiums paid during the year for each 2% shareholder-employee and their family. We will include them in the fourth-quarter and annual payroll reports and on the W-2.
- If another service prepares your payroll: give your provider the same total before your last payroll of the year.
Contact our office with any questions.
Team Reason
Sources: IRS, S Corporation Compensation and Medical Insurance Issues; IRS Notice 2008-1; EDD, Taxability of Employee Benefits (DE 231EB).
Disclosure
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. Any company names noted herein are for educational purposes only.
All information is believed to be from reliable sources; however we make no representation as to its completeness or accuracy. All economic and performance data is historical and not indicative of future results. Market indices discussed are unmanaged. Investors cannot invest in unmanaged indices. Additional risks are associated with international investing, such as currency fluctuations, political and economic instability and differences in accounting standards.
Investing in securities in emerging markets involves special risks due to specific factors such as increased volatility, currency fluctuations and differences in auditing and other financial standards. Securities in emerging markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments.
An index is a statistical measure of change in an economy or a securities market. In the case of financial markets, an index is an imaginary portfolio of securities representing a particular market or a portion of it. Each index has its own calculation methodology and is usually expressed in terms of a change from a base value. Thus, the percentage change is more important than the actual numeric value. An investment cannot be made directly into an index.
Investing in fixed income securities involves credit and interest rate risk. When interest rates rise, bond prices generally fall. Investing in commodities may involve greater volatility and is not suitable for all investors. Investing in a non-diversified fund that concentrates holdings into fewer securities or industries involves greater risk than investing in a more diversified fund. The equity securities of small companies may not be traded as often as equity securities of large companies so they may be difficult or impossible to sell. Neither diversification nor asset allocation assure a profit or protect against a loss in declining markets. Past performance is not an indicator of future results.
Financial Planning offered through Reason Financial, a state Registered Investment Advisor. Investment advice offered through Merit Financial Group, LLC an SEC Registered Investment Advisor. Merit Financial Group and Reason Financial are separate entities. Tax related services offered through Reason Tax Group. Reason Tax Group is a separate legal entity and not affiliated with Merit Financial Group, LLC. Sean P. Storck CA Insurance Lic#OF25995 and Steven W. Pollock CA Insurance Lic#OE98073
Copyright © 2026 Reason Financial all rights reserved.
Continue Reading
An Economic and Market Update: Q4 2026
AN ECONOMIC AND MARKET UPDATE Q4 2026 / July 1 – September 30, 2026 EXECUTIVE SUMMARY Last quarter, we wrote…
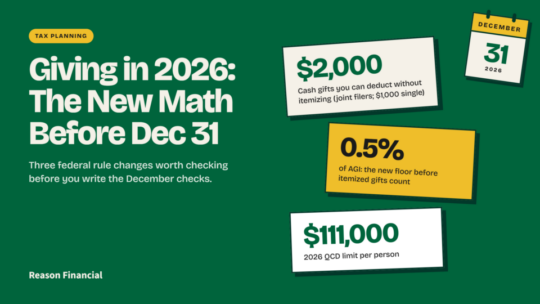
Giving in 2026: What the New Charitable Rules Change Before December 31
Charitable rules change in 2026 for itemizers, non-itemizers and QCDs. What changed, and what families should review with Reason Tax before December 31.
The Longest Commute in San Diego: Gray Whales, Point Loma, and a 10,000 Mile Round Trip
Gray whales pass Point Loma each winter on a roughly 10,000-mile round trip. When to look, how to spot them, and why San Diego gets the best front-row seat.