Hybrid Long-Term Care: Coverage That Isn’t Wasted + Tax-Smart Way to Fund It
Long-term care has come up in more of our client conversations this year than usual, often when someone is helping a parent through it and begins to think about their own plan. It is one of the most important questions in retirement planning: if you need care someday, how will you pay for it without disrupting everything else you have built? The encouraging news is that the ways of answering that question have improved. The long-term care insurance many people remember, where you pay premiums for years and receive nothing back if you never file a claim, is no longer the only choice.
HOW ASSET-BASED LONG-TERM CARE WORKS
Asset-based (or “hybrid”) long-term care starts with an asset instead of a premium. You reposition a lump sum (an existing annuity, an old cash-value life policy, or idle cash) into a policy that combines an insurance chassis with a long-term care benefit. From there, one of three things happens, and all three of them are acceptable outcomes.

Source: Reason Financial. Illustrative only — benefits, leverage, and options vary by contract and carrier.
If you need care, the policy typically pays long-term care benefits worth a multiple of what you put in. If you never need care, a life-based policy passes a death benefit to your heirs, and an annuity-based policy keeps its account value growing for you. And if you change your mind, many contracts include a return-of-premium feature. Many policies are designed to provide value even if long-term care benefits are never used, although features and outcomes vary by contract.
THE TAX ANGLE CONGRESS BUILT IN
This is where it gets genuinely interesting for anyone holding an old annuity with built-up gains which is why we’re covering this in the same breath as tax planning. Since 2010, under rules created by the Pension Protection Act, a deferred annuity’s value that is used to pay for qualified long-term care can come out income-tax-free. Two mechanics do the work:
- A 1035 exchange lets you move an existing annuity into an annuity with a qualified long-term care rider (or into a standalone qualified long-term care policy) with no tax due on the transfer. Your gains ride along untouched.
- Once there, charges and benefits for qualified long-term care are not treated as taxable distributions. Gains that would have been taxed as ordinary income if you’d simply cashed out can instead fund costs of care without the IRS ever taking its cut.
Compare that to the default path. Withdraw from a deferred annuity the ordinary way and the gains come out first, taxed as ordinary income.
A WORKED EXAMPLE
Picture this: you bought a $60,000 deferred annuity years ago and it’s now worth $100,000. You have no income plans for it, it’s your just-in-case money. If a care need arises and you cash it in to pay the bills, roughly $40,000 of gain lands on your tax return as ordinary income; depending on your bracket, that could cost $8,000 to $14,000 in federal tax alone, right when expenses are spiking. If instead you had exchanged it (tax-free, under Section 1035) into an annuity-based long-term care policy, that same $100,000 could typically support a meaningfully larger pool of care benefits, and every dollar used for qualified care comes out income-tax-free. Same money, same purpose, very different outcome.
WHO THIS FITS – AND WHEN TO HOLD OFF
The best candidates look like this: you’re roughly 55 to 75, you hold an old annuity or cash-value policy (or a cash reserve) you’ve mentally set aside for emergencies, and your plan for long-term care is currently “we’ll figure it out.” Asset-based designs also tend to use simplified underwriting, which can work for people who would struggle to qualify for traditional long-term care insurance.
It’s not for everyone. Hold off if repositioning the money would leave you thin on liquidity. These policies want to be left alone, and surrender charges apply in the early years. If you have significant health issues, underwriting may still limit your options. And if you already carry traditional long-term care coverage, the math of switching rarely pencils.
WHAT TO DO NEXT
If you own an annuity that has not been reviewed in some time, we would welcome the opportunity to assess whether it remains appropriately positioned for your objectives. A practical first step is to gather your most recent statement and note the current value and original cost basis. We will review the contract in the context of your broader financial plan and coordinate with your tax professional at Reason Tax before any action is taken.
Sources: Pension Protection Act of 2006 (provisions effective January 1, 2010, including Internal Revenue Code §72(e)(11), §7702B, and §1035 exchange rules); Internal Revenue Service guidance on qualified long-term care contracts.
Disclosure
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. Any company names noted herein are for educational purposes only.
All information is believed to be from reliable sources; however we make no representation as to its completeness or accuracy. All economic and performance data is historical and not indicative of future results. Market indices discussed are unmanaged. Investors cannot invest in unmanaged indices. Additional risks are associated with international investing, such as currency fluctuations, political and economic instability and differences in accounting standards.
Investing in securities in emerging markets involves special risks due to specific factors such as increased volatility, currency fluctuations and differences in auditing and other financial standards. Securities in emerging markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments.
An index is a statistical measure of change in an economy or a securities market. In the case of financial markets, an index is an imaginary portfolio of securities representing a particular market or a portion of it. Each index has its own calculation methodology and is usually expressed in terms of a change from a base value. Thus, the percentage change is more important than the actual numeric value. An investment cannot be made directly into an index.
Investing in fixed income securities involves credit and interest rate risk. When interest rates rise, bond prices generally fall. Investing in commodities may involve greater volatility and is not suitable for all investors. Investing in a non-diversified fund that concentrates holdings into fewer securities or industries involves greater risk than investing in a more diversified fund. The equity securities of small companies may not be traded as often as equity securities of large companies so they may be difficult or impossible to sell. Neither diversification nor asset allocation assure a profit or protect against a loss in declining markets. Past performance is not an indicator of future results.
Financial Planning offered through Reason Financial, a state Registered Investment Advisor. Investment advice offered through Merit Financial Group, LLC an SEC Registered Investment Advisor. Merit Financial Group and Reason Financial are separate entities. Tax related services offered through Reason Tax Group. Reason Tax Group is a separate legal entity and not affiliated with Merit Financial Group, LLC. Sean P. Storck CA Insurance Lic#OF25995 and Steven W. Pollock CA Insurance Lic#OE98073
Copyright © 2026 Reason Financial all rights reserved.
Continue Reading
An Economic and Market Update: Q4 2026
AN ECONOMIC AND MARKET UPDATE Q4 2026 / July 1 – September 30, 2026 EXECUTIVE SUMMARY Last quarter, we wrote…
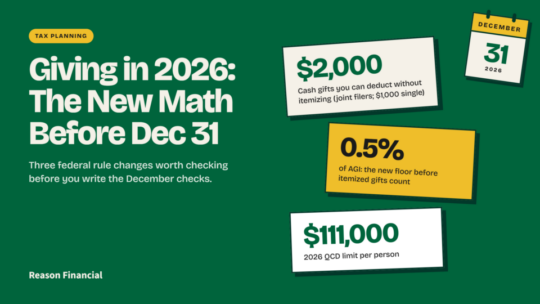
Giving in 2026: What the New Charitable Rules Change Before December 31
Charitable rules change in 2026 for itemizers, non-itemizers and QCDs. What changed, and what families should review with Reason Tax before December 31.
The Longest Commute in San Diego: Gray Whales, Point Loma, and a 10,000 Mile Round Trip
Gray whales pass Point Loma each winter on a roughly 10,000-mile round trip. When to look, how to spot them, and why San Diego gets the best front-row seat.