Retirement Planning for Clarity and Confidence
Retirement is a transition in how money works for you: from accumulation to income, from employer benefits to personal decisions about Social Security, healthcare, and taxes. At Reason Financial, we partner with you to design a tax-smart retirement plan that answers practical questions.
From Saving to Living: What Changes at Retirement
How much can you spend? Which accounts should fund which years? How do you stay prepared for healthcare costs and still leave an intentional legacy? Fewer surprises. Better decisions. That is the aim: Confidence to Live Fearless and Free in the years you have worked toward.
During the working years, the main levers are often contribution rates, asset allocation, and tax drag. In retirement, order of withdrawals, Social Security timing, Medicare choices, required distributions, and the interaction between taxable, tax-deferred, and tax-free accounts can matter as much as market return.
Our Financial Advice practice already frames retirement as one of life’s central milestones. This page goes deeper on the distribution chapter: turning pensions, 401(k)s, IRAs, taxable brokerage, and other assets into a coherent income plan without treating taxes as an afterthought.
Trusted by Families Nationwide
Together with our clients, we've built lasting relationships and meaningful results.
25+ Years
Experience that lasts
Hundreds
Clients and families nationwide
CFP® · CPA · EA
CFP®, CPA, and EA professionals working together
How We Approach Retirement Planning
Income and cash-flow design
We begin with what the money is for: lifestyle, travel, family support, healthcare buffers, and gifts or bequests. Detailed cash-flow projection helps identify a sustainable spending path and a written sequence for where dollars come from each year. Where appropriate, income may blend portfolio distributions, pension payments, Social Security, and other sources. The goal is clarity about what lands in checking, and why.
Tax-aware withdrawals and contributions
Every financial decision is also a tax decision. In the years before retirement, contribution strategy (including workplace plans and IRAs) and Roth conversions in the right brackets can shape future flexibility. In retirement, balancing withdrawals across taxable, tax-deferred, and tax-free accounts can help manage annual brackets and reduce unnecessary tax drag over a lifetime. Our tax philosophy on the Tax Planning & Preparation page is explicit: retirement optimization is part of proactive, year-round planning, and minimizing tax this year is not always the right answer if it harms later years.
Healthcare and longevity considerations
Leaving employer coverage for Medicare is a planning event. We help clients model projected healthcare costs and coverage timing in retirement cash flow, and discuss how supplemental options may fit the plan. Longevity and long-term care risk are part of the conversation when relevant. We do not enroll clients in Medicare. Product choices, if any, depend on your situation and available licenses; we do not invent guarantees.
Portfolio alignment for the distribution years
As spending begins, risk tolerance and liquidity needs often change. Investment planning stays tax-aware: where assets are held, how gains and losses are managed, and how rebalancing supports withdrawals. Our Investment Management platform and Merit Financial Group relationship support institutional research and portfolio construction. The retirement plan and the portfolio should not fight each other.
Legacy and wealth transfer
Retirement planning and estate planning meet at beneficiary designations, charitable intent, and what remains after a lifetime of spending. We connect that work to our Estate Planning advisory approach: coordinating with your estate attorney on documents, while we help keep titling, beneficiaries, and tax location aligned with your values.
Who This Work Often Serves
We partner with people who value thoughtful guidance and intentional living. On our Why Reason page, illustrative composite scenarios include families planning toward a comfortable retirement, professionals with complex pay, entrepreneurs building retirement through business and plan design, and recent retirees turning savings into reliable income. Your results depend on your circumstances. Those composites are educational, not promises.
Whether you are ten years out, one year out, or already drawing income, the same discipline applies: define goals, model cash flow and taxes together, implement, and adapt when life or law changes.
Connected to the Rest of Your Plan
Our Guided Advice Process
- Discover your goals.We start with what the money is for in retirement: lifestyle, family, healthcare, and legacy.
- Design your plan.Investments and tax picture belong in the same model so withdrawal strategy and portfolio design reinforce each other.
- Put it into action.Accounts, transfers, Social Security claiming decisions, healthcare cost assumptions, and implementation steps follow the written plan.
- Stay connected.Secure portals and reporting keep balances and progress visible.
- Adapt along the way.Markets, health, family needs, and tax law change. Because we also prepare tax returns for many clients, we often see planning opportunities before they appear elsewhere.
Frequently Asked Questions
When should we start retirement planning with Reason?
Whether you are years out or already drawing income, we model cash flow, taxes, and portfolio design together and adapt as life and law change.
How do taxes factor into retirement income?
Contribution strategy, Roth conversions when appropriate, and withdrawal order across taxable, tax-deferred, and tax-free accounts are part of year-round planning with our tax team.
Do you help with Social Security and Medicare decisions?
We discuss claiming timing and healthcare cost planning in context of your income plan. Product and enrollment choices depend on your situation; we do not invent guarantees.
How does retirement planning connect to estate planning?
Drawdown, beneficiaries, and legacy goals meet on our Estate Planning page. We coordinate advisory work with your estate attorney on documents.
How do we get started?
Contact or (858) 483-7500, Mon-Fri 9-5, 4747 Morena Blvd Ste 102, San Diego CA 92117.
A First Conversation
A first conversation costs nothing and covers a lot: your retirement timeline, your accounts, your tax picture, and whether we are the right partner. Call us, email us, or schedule a conversation online.
Prefer the phone? (858) 483-7500. Office hours are Monday through Friday, 9:00 AM to 5:00 PM. We are based at 4747 Morena Blvd, Ste 102, San Diego, CA 92117.
Stay Informed with Quarterly Research & Insights
Meet the Financial and Tax Professionals
Our experienced team is dedicated to helping you achieve your financial and tax goals with personalized advice and comprehensive services.




Research and Insights
3rd Quarter 2026 – Economic and Market Update
Q2 2026 in review: the S&P 500's best quarter since 2020, oil's round trip from $114 back to $70, a 4.2% CPI print that…
Read more
America at 250: A Birthday Worth Sitting With for a Moment
The United States just turned 250 — and the story reads surprisingly well as a series of 50-year check-ins. Founding-era population the size of…
Read more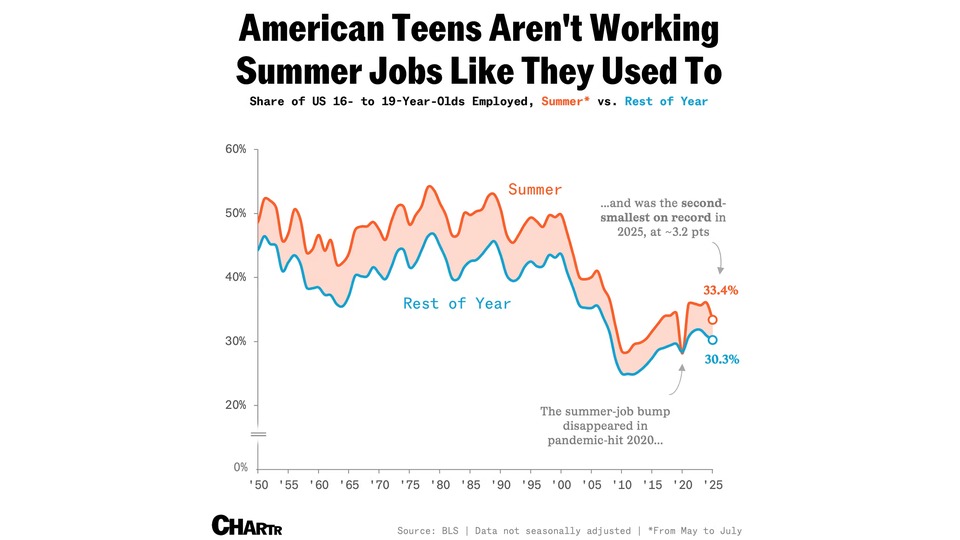
American Teens Aren’t Working Summer Jobs Like They Used To
This Chartr line chart tracks the share of U.S. 16- to 19-year-olds who were employed from 1950 through 2025, split into summer (May to…
Read more